Climate change risks are part of Taiwan Mobile's material risks. Given their potential material financial impact on business operations, Taiwan Mobile took inventory of and disclosed climate change risks and opportunities according to the Task Force on Climate-related Financial Disclosures (TCFD) framework, enabling related stakeholders to grasp climate change risks and opportunities and their financial impact more systematically.
*NoteIn 2023, TWM has held three inter-departmental TCFD workshops, and the first TCFD report will be published to fully reveal the implementation of climate-related risks and opportunities management through the four directions of Governance, Strategy, Risk Management, Indicators and Targets.
A comprehensive governance structure oversees all climate-related risks and opportunities. The roles and responsibilities of the respective governance bodies are outlined as follows:
Board of Directors: Oversees climate-related risks and opportunities faced by the Company and conducts an annual review.
ESG Steering Committee: Chaired by the Chairman of the Board, with five independent directors serving as committee members. The committee meets twice a year to oversee ESG-related decision-making, including strategies and targets for climate-related risks and opportunities, and reports to the Board of Directors.
Chief Sustainability Officer (Highest-Ranking Management Position with Climate Responsibility): To reinforce executive-level climate governance, TWM established the Chief Sustainability Officer (CSO) position, held concurrently by the President (Jamie Lin), serving as the highest-ranking executive with dedicated management responsibility for assessing, managing, and executing climate-related strategies. The CSO leads the company-wide net-zero transition roadmap (including SBTi 1.5°C targets, RE100, and EV100), oversees cross-departmental climate risk assessments and mitigation investments, and directly reports progress and strategic recommendations to the ESG Steering Committee and the Board of Directors.
Risk Management Steering Committee: Composed of senior executives appointed by the Chairman as committee members. The committee meets twice a year to evaluate and approve mitigation and adaptation plans based on risk control mechanisms. It periodically reports corporate risks—including climate-related risks—to the Audit and Risk Management Committee, the ESG Steering Committee, and the Board of Directors.
Environmental Working Group: Chaired by the Chief Technology Officer, with the Head of the Sustainability Department serving as the deputy chairperson. The group meets every six months to identify and manage climate-change risks and opportunities in accordance with the Company's risk management system, and reports climate risk trends and issues to the Risk Management Steering Committee and the ESG Steering Committee.
ESG Working Group: Chaired by the Chief Sustainability Officer (President), and the top executive of each business group is a member. The working group meets four times a year to conduct research on international climate risk trends and provide feedback on the latest risk trends to the Environmental Working Group.
Important climate-related initiatives, such as SBT, EV100, RE100, Net Zero, TCFD and TNFD analyses and publications, are reviewed every six months by the Environmental Working Group, and quarterly by the ESG Working Group. These resolutions undergo further review by the ESG Steering Committee before being submitted to the Board of Directors. These multiple layers of reviews and governance ensure that policies are communicated top-down and actively planned and reported bottom-up.
Climate-Related Management Incentives
The president (Chief Executive Officer, CEO): Set the individual annual KPIs as supervised the company's overall carbon reduction. CEO achieved the objective will directly align one's performance-based bonuses.
Technology Executives Officers (CTO): Incorporated energy efficiency, carbon reduction, and renewable energy usage into individual annual KPI, and the performance will directly influence one's performance-based bonuses.
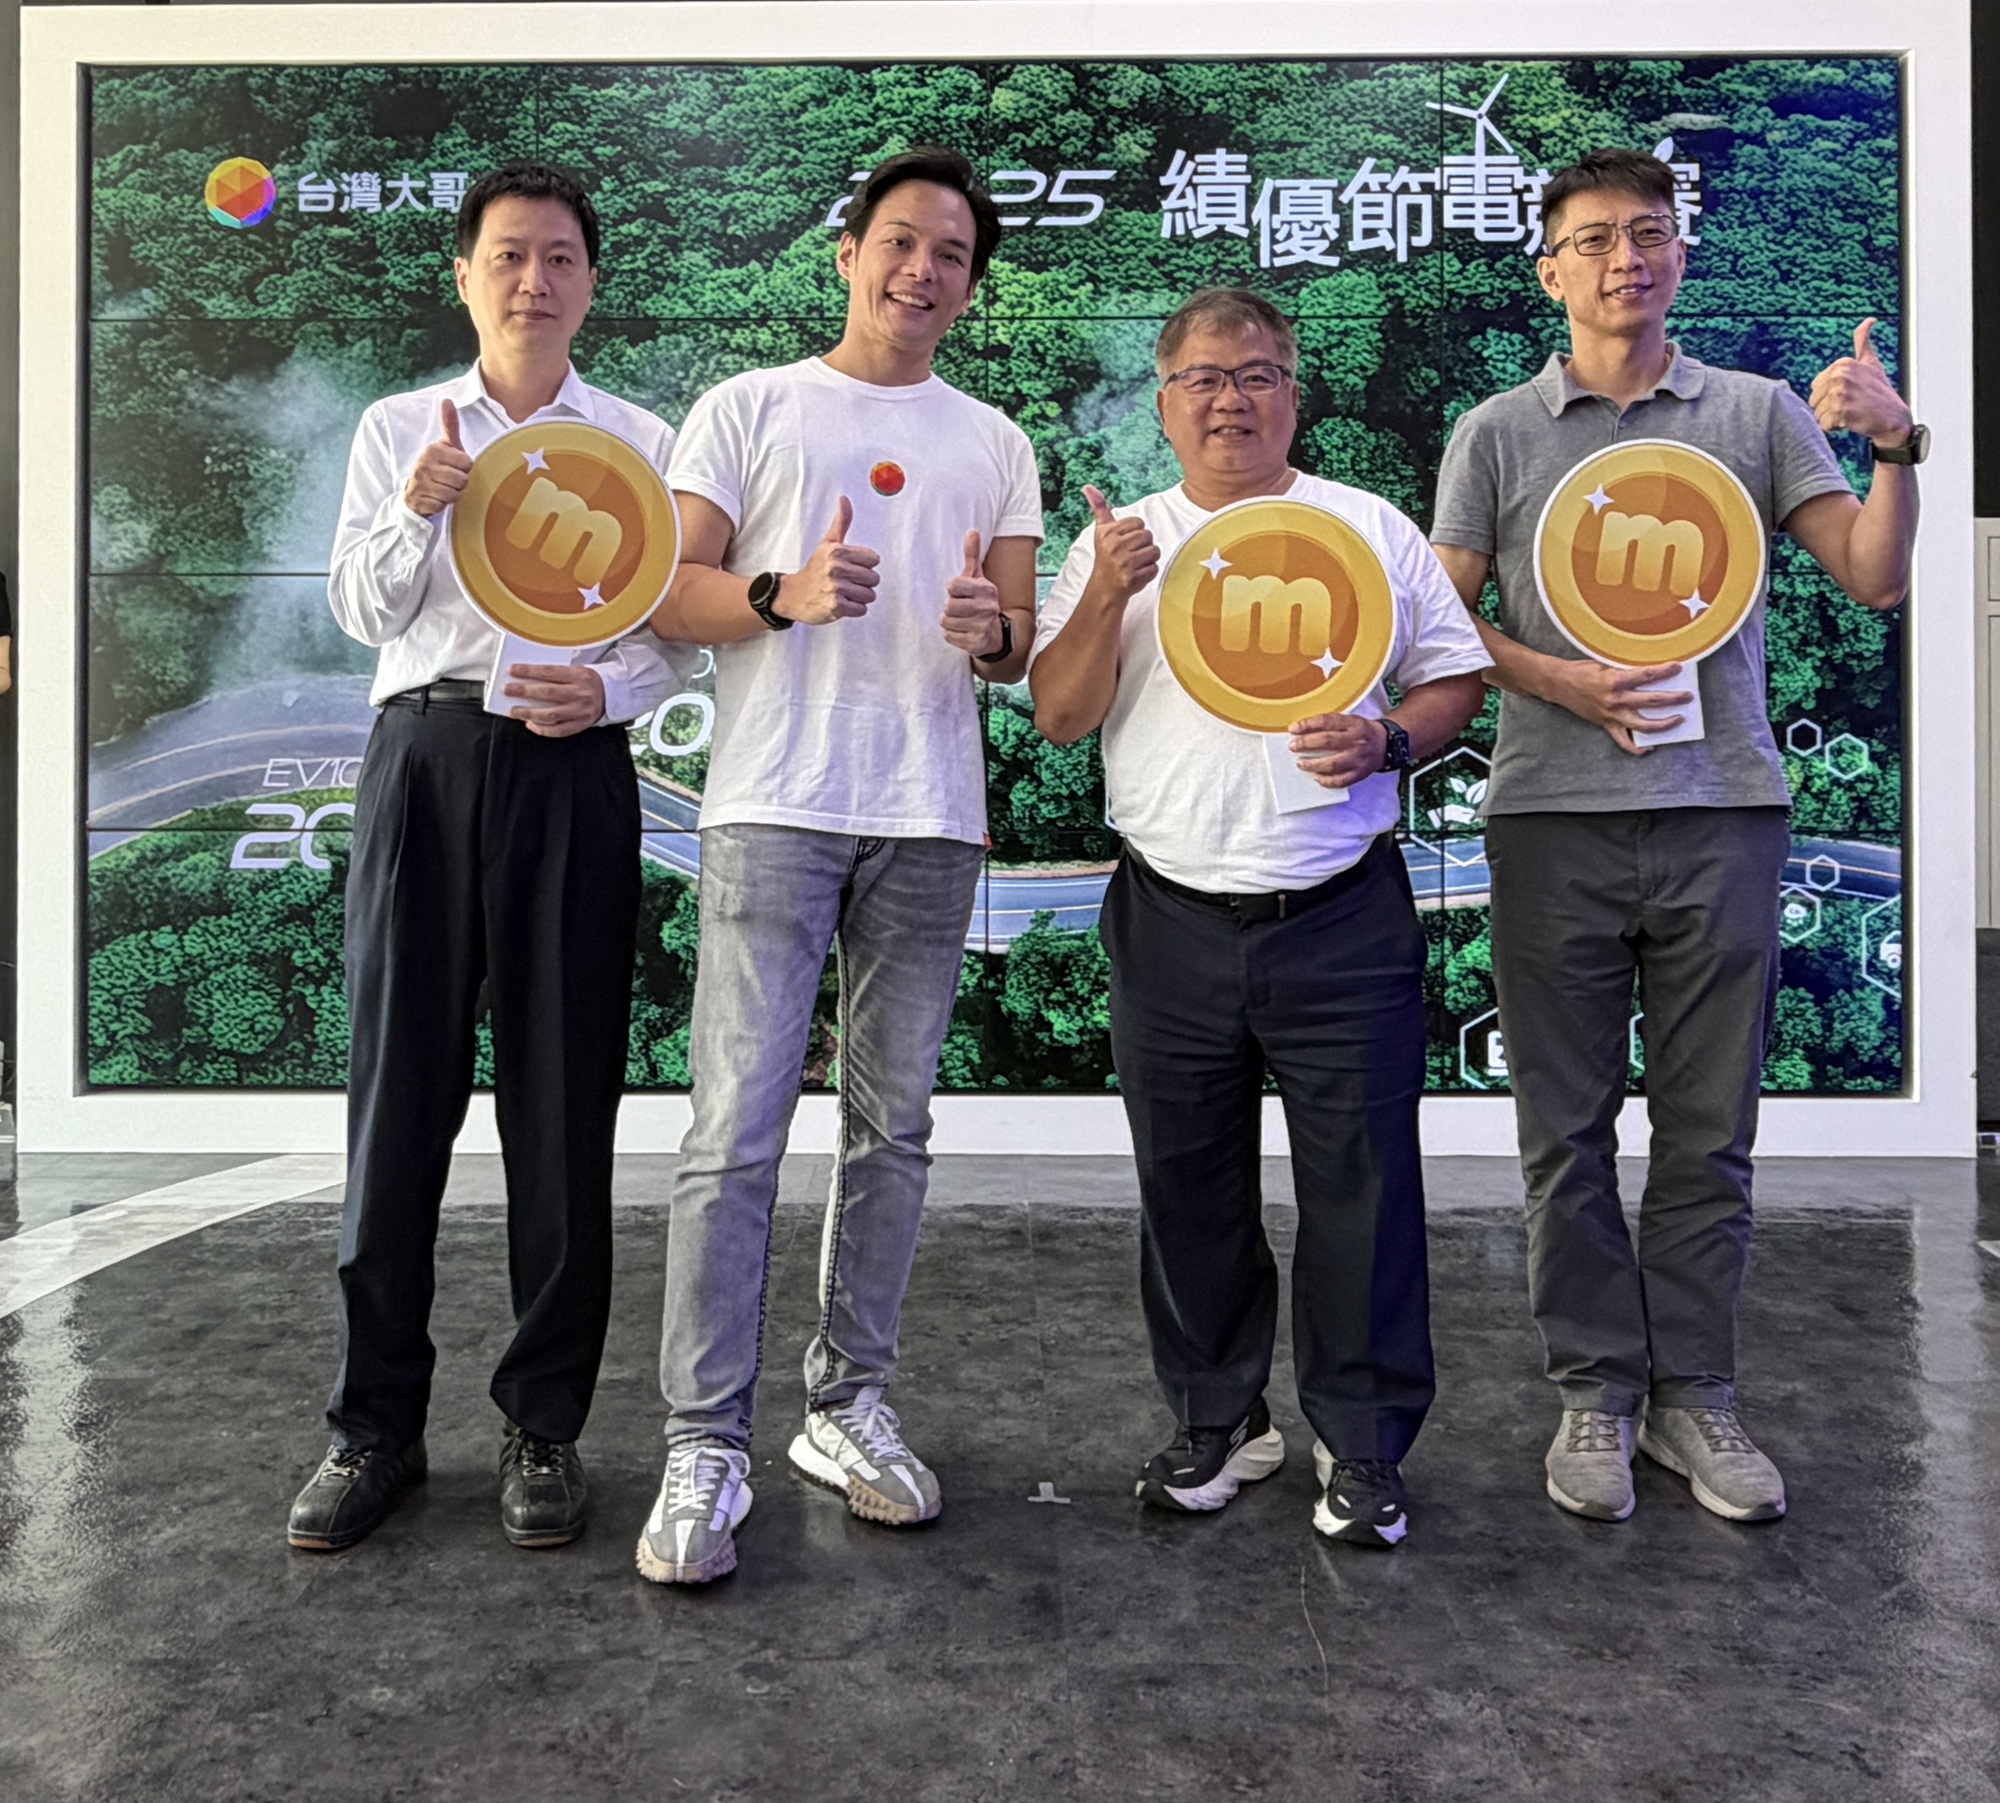
The Company-wide Energy Conservation Competition: The technical and non-technical units will compete energy conservation annually. Managers and employees from the units that conserves the largest amount of energy throughout the year will be publicly praised and awarded by the CEO. The result of 2025 Energy Conservation Competition as following:
Strategy
Taiwan Mobile defines its short-, medium-, and long-term time horizons through its enterprise risk management and sustainability governance processes. As part of the Company's adoption of IFRS Sustainability Disclosure Standards (IFRS S1 and S2), Taiwan Mobile established an IFRS Sustainability Disclosure Project Team and integrated sustainability-related risk and opportunity assessment into its existing COSO ERM framework. The Company defines short-term as 1–5 years, medium-term as 6–10 years, and long-term as 11–24 years. These time horizons are aligned with Taiwan Mobile's strategic planning cycle, decarbonization roadmap, climate scenario analysis, and long-term sustainability commitments. Drawing on international research, industry trends, SASB sector-specific topics, stakeholder input, and internal business considerations, Taiwan Mobile identifies and evaluates environmental dependencies, impacts, risks, and opportunities across different time horizons. The defined time horizons support the assessment of potential effects on business operations, strategy, resource allocation, investment planning, financial performance, and long-term enterprise value. Assessment results are incorporated into strategic and financial planning processes and reviewed through the Company's governance mechanisms, including Board-level oversight.
Cross-departmental discussion and identification of significant climate risks and opportunities that have a direct/indirect financial impact on the Company in the short, medium, and long term and input into management practices.
Transformation Scenario Analysis: Evaluate the potential financial impact and input management practices of businesses in three external transformation scenarios (including governmental net-zero path, SSP1-1.9 and SBT net-zero emissions).
Actual Scenario Analysis: Evaluate four climate models (including RCP2.6, RCP4.5, RCP6.0, and RCP8.5) with extreme rainfall under climate change as the hazard level, extreme rainfall-induced flooding, landslides, and mudslides as the vulnerability level, and the location of owned assets and supplier locations as the exposure level for the actual risk value analysis.
Risk Management
Participants in the TCFD workshop are divided into groups according to their operational attributes, and follow the TCFD framework to identify climate risks. 36 climate risks and 22 opportunities are presented in the value chain, and their impact type, scope, intensity, time of occurrence and likelihood are analyzed.
Establish a matrix of climate risks and opportunities, and classify the impact level of the matrix as 'moderate to high' or higher and the probability as 'possible' or higher as significant risks and opportunities; based on the results of the identification and ranking of climate risks and opportunities, report the assessment results and response plans of climate-related risks and opportunities.
In addition to completing the greenhouse gas inventory for the first, second and third categories, TWM has also set short-, medium- and long-term greenhouse gas reduction targets, renewable energy use targets and practices to enhance the resilience to climate change. The relevant targets and adaptation practices are as follows:
Targets
Enhanced Climate Financial Impact Disclosure: See the TCFD report planned for publication in 2023 for details of quantified projects in 2022; 1 quantified in 2021; 2 quantified in 2019.
EV100 by 2030: Achieve EV100 by 2030 (reaching 13% in 2025).
RE100 by 2040: Achieve RE100 by 2040 (reaching 18.6% in 2025).
Net-Zero Emissions by 2050: Achieve net-zero emissions by 2050 (with a 16.3% carbon reduction compared to the 2024 baseline year).
Climate Risks assessment
Taiwan Mobile identified climate risks in 2022 that had a significant impact on operations or finances are transition risks, such as cap and trade, carbon tax, and renewable energy regulations, also including legal risk. TWM also has conducted an in-depth assessment of the potential impact of climate change on intensity, value chain stages, time horizon, and financial impact for the five major climate risks, and carried out management responses. As below table:
Type of risk
No.
Risk level
Explanation of Risk
Location of occurrence
Time horizon
Type of impact
Financial Impact
Management practices
Management costs
Transition
1
Medium-high
Cap & Trade
Organization itself
Short to medium term
Indirect cost increase
SSP1_1.9
2030: The estimated carbon emissions are 283,000 metric tons, and the regulations require an annual total reduction of 4.2%, assuming a 4.2% reduction in 2030, that is, 271,000 metric tons should be achieved; therefore, the payment for excess emissions is NTD 3.56 million
2035: The estimated carbon emissions are 252,000 metric tons, and the regulations require an annual total reduction of 4.2%, assuming a reduction of 21% in 2035 compared to 2030, that is, 223,000 metric tons should be achieved; therefore, the payment for excess emissions is NTD 8.53 million
SSP1-2.6
2030: The estimated carbon emissions of the Company are 283,000 metric tons, and the regulations require an annual total reduction of 2.5%, assuming a 2.5% reduction in 2030, that is, 276,000 metric tons should be achieved; therefore, the payment for excess emissions is NTD 2.12 million
2035: The estimated carbon emissions of the Company are 252,000 metric tons, and the regulations require an annual total reduction of 2.5%, assuming a reduction of 12.5% in 2035 compared to 2030, that is, 248,000 metric tons should be achieved; therefore, the payment for excess emissions is NTD 1.31 million
SSP2-4.5
2030: The estimated carbon emissions of the Company are 283,000 metric tons, and the regulations require an annual total reduction of 1.23%, assuming a 1.23% reduction in 2030, that is, 279,000 metric tons should be achieved; therefore, the payment for excess emissions is NTD 1.04 million
2035: The estimated carbon emissions of the Company are 227,000 metric tons, and the regulations require an annual total reduction of 1.23%, assuming a reduction of 6.15% in 2035 compared to 2030, that is, 265,000 metric tons should be achieved by TWM; therefore, the payment is not required
Outsourcing of renewable energy
In response to the total emission control, TWM must try to reduce
carbon emissions. If the management target for 2030 is set as 20% of the
total renewable energy use, which can be converted into 61 million KWh
of renewable energy use, and the unit price per KWh is NTD 6, the
estimated input cost will increase by about NTD 366 million.
Transition
6
Medium
Carbon tax
Organization itself
Short to medium term
Direct cost increase
For the amount of tax levied on carbon emissions, assuming there are no basic emissions, based on the carbon tax of NTD 300/ton in 2021, and using the IPCC SSP1-1.9 scenario where the temperature rise is maintained at 1.5°C, the estimated financial impact is as follows according to the annual growth rate of carbon tax: Scenario 1: Non-nuclear home
2030: the estimated carbon emissions are 283,000 metric tons, and a carbon tax of NTD 430 million needs to be paid
2035: the estimated carbon emissions are 252,000 metric tons, and a carbon tax of NTD 523 million needs to be paid
2040: the estimated carbon emissions are 214,000 metric tons, and a carbon tax of NTD 565 million needs to be paid
Scenario 2: Extended service of nuclear energy
2030: the estimated carbon emissions are 260,000 metric tons, and a carbon tax of NTD 394 million needs to be paid
2035: the estimated carbon emissions are 227,000 metric tons, and a carbon tax of NTD 472 million needs to be paid
2040: the estimated carbon emissions are 189,000 metric tons, and a carbon tax of NTD 499 million needs to be paid
Scenario 3: Plan of the Energy Bureau
2030: the estimated carbon emissions are 253,000 metric tons, and a carbon tax of NTD 384 million needs to be paid
2035: the estimated carbon emissions are 211,000 metric tons, and a carbon tax of NTD 438 million needs to be paid
2040: the estimated carbon emissions are 163,000 metric tons, and a carbon tax of NTD 429 million needs to be paid
Green power directly transmitted to TWM
According to the Company's 2040 RE100 path, the estimated management
costs (assuming the transfer-supply mode is adopted and the mean price
of green electricity is NTD 6 per kWh) are as follows:
Transition
7
Medium-high
Compulsory declaration
Organization itself
Long-term
Direct cost increase
Penalty for failure to declare on time SSP1-1.9
2030: NTD 32 million
2040: NTD 72 million
2050: NTD 112 million
SSP1-2.6
2030: NTD 24 million
2040: NTD 54 million
2050: NTD 84 million
SSP2-4.5
2030: NTD 16 million
2040: NTD 36 million
2050: NTD 56 million
Internal and external labor costs for checking and declaration
2030: NTD 6.3 million
Transition
9
Medium-high
Product efficiency regulations and standards
Upstream & Organization itself
Short-term
Direct cost increase
SSP1-1.9
2030: NTD 3.06 billion
2040: NTD 8.86 billion
2050: NTD 14.64 billion
SSP1-2.6
2030: NTD 320 million
2040: NTD 1.16 billion
2050: NTD 2.24 billion
SSP2-4.5
2030: NTD 53.75 million
2040: NTD 120 million
2050: NTD 290 million
Consulting
2030: NTD 15 million
Transition
34
High
Renewable energy regulations
Organization itself
Short-term
Rise in energy prices
Amount of expenditure on outsourcing of renewable energy due to compulsory regulations SSP1-1.9
In line with the government's 2050 net zero policy, it is expected that the use ratio of renewable energy needs to reach 100% in 2050.
The total consumption of renewable energy required is about 730 million kWh, and the penalty is calculated based on the payment of electricity fees (NTD 4/kWh), which will increase the electricity cost by about NTD 3 billion.
SSP1-2.6
It is expected that by 2030, a certain percentage of renewable energy will be added to the business premises with a single contract capacity >100 kW.
Taking 10% as the basis for calculation, an inspection shows that about 30 premises will be affected, with a total contract capacity of 5,373 kW.
A total of 537.3 kWp of renewable energy will be installed, and the penalty will be calculated based on the payment of electricity fees, that is, 537.3 kWp*2,500 kWh/kWp*NTD 4, which is approximately NTD 5 million.
SSP2-4.5
It is expected that by 2025, a certain percentage of renewable energy will be added to the business premises with a single contract capacity >800 kW.
Taking 10% as the basis for calculation, an inspection shows that a total of 2 premises will be affected: 4,990 kW for cloud IDC and 3,150 kW for optoelectronic machine room.
499 kWp and 315 kWp of renewable energy will be used respectively, and the penalty will be calculated based on the payment of electricity fees, that is, (499+315) kWp*2,500 kWh/kWp*NTD 4, which is approximately NTD 8 million.
Base Stations: A total of 740 units of highly weatherproof Note 1 power supply systems (SMR) are used to prevent operation interruptions caused by drastic temperature changes.
Cloud Internet Data Center(IDC): Equipped with generators, uninterruptible power supply system, and n+1 redundancy system to avoid service interruption due to disaster.
Mobile Broadband Mobile Service Stations: 25 mobile broadband mobile service stations have been built to avoid the disconnection of cell towers due to disasters.
Mobile Communication Platform for Disaster Relief: Build 17 fixed mobile communication platforms with more than 72 hours of power backup for disaster prevention and relief, and optimize 10 existing mobile communication platforms to facilitate emergency mobile communication services in disaster areas.
Note 1Acceptable ambient temperature 0~65 degree Celsius. For More Adaptive Practices Please Refer to TWM's TCFD Report